Special Reports | Autumn 2026 Edition: High-Stakes Regulatory & Strategic Advocacy
The Interview
The Cost of Compliance: Geopolitical Tariffs, Supply Chain Strains, and the Future of European Industrial Tech
How tariffs and regulatory uncertainty are reshaping Europe's industrial future.
With Thomas Linget, Executive Director at logos
By Aida Iordache · October 21, 2026
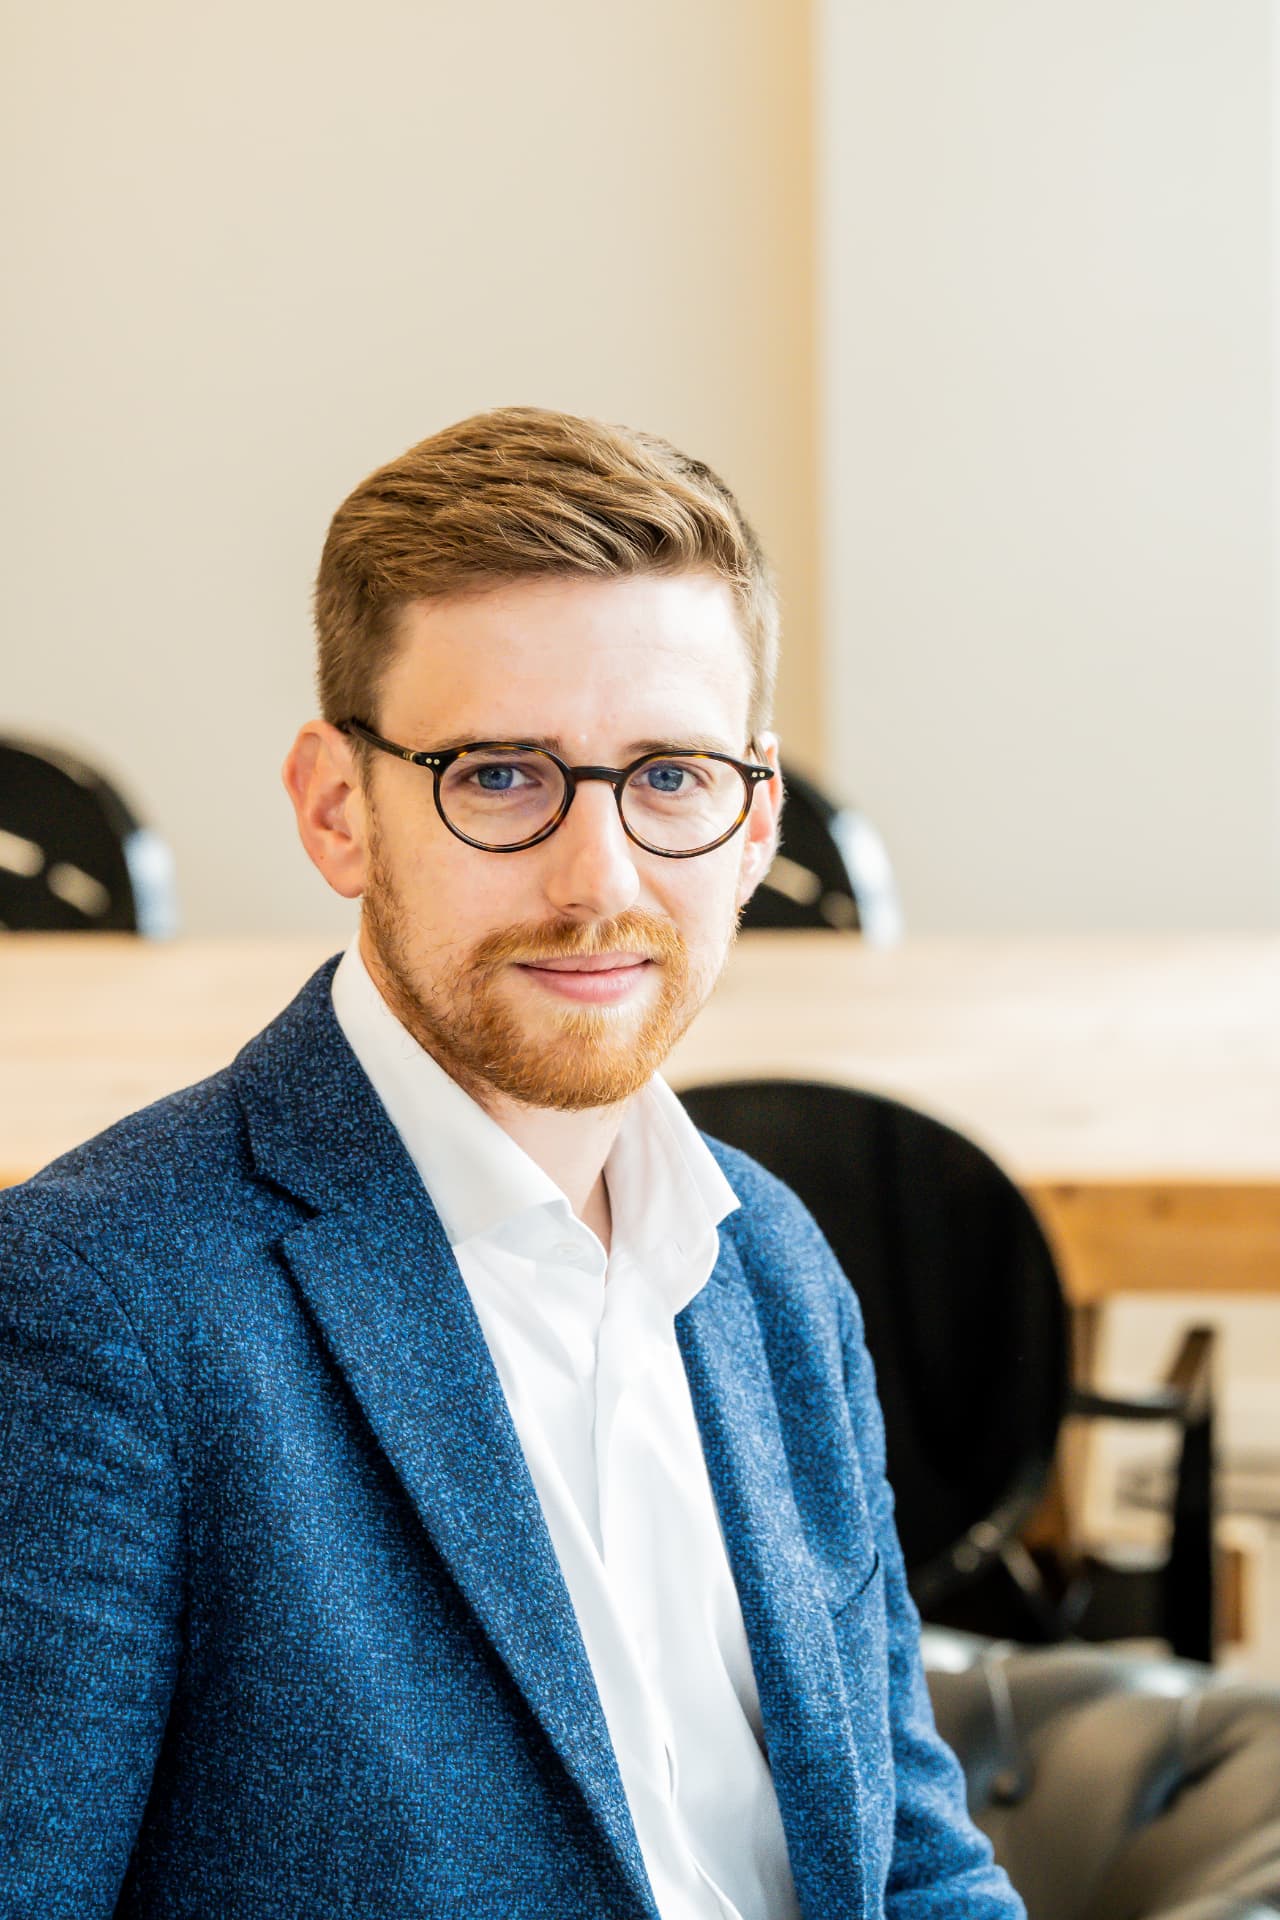
The European automotive and digital sectors are no longer just navigating a transition; they are caught in a regulatory collision course. As profit margins in the US and China tighten under geopolitical tariffs, European manufacturers face an asymmetric challenge on their own turf from heavily subsidized global competitors, all while managing an unstable political majority in the European Parliament.
To decode these shifting fault lines, The Gazette sat down with Thomas Linget, Executive Director at logos.
As one of the most agile and authoritative public affairs consultancies driving industrial strategy in the EU Bubble, logos has built a formidable reputation for tracking complex regulatory friction. Operating from the frontline of Brussels advocacy, Linget’s leadership provides corporate boards with the raw, anticipatory intelligence required to align supply chains and enterprise design before critical legislative windows are permanently locked in.
1. The Future of Sustainable Mobility Regulations
The Gazette: With the EU pushing for aggressive decarbonization and stricter corporate sustainability standards, what do you see as the biggest regulatory hurdle for traditional automotive and mobility industries trying to transition to green compliance?
Thomas Linget: The problem doesn’t come from just one single regulation, but from many colliding at a time when the business is already under strain from multiple angles.
The European automotive industry is caught between a rock and a hard place. The export markets that used to deliver margins, mainly the US and China, now offer limited prospects due to trade tariffs and stronger domestic competition. At the same time, Chinese OEMs are now competing on Europe’s own turf on EVs and PHEVs, for which state-of-the-art batteries (which account for 20-40% of the value) still have to be sourced largely from outside Europe.
The EU is attempting to respond with the Industrial Accelerator Act and “Made in Europe” criteria, coupled with conditionality on eligibility criteria for greening corporate fleets, flexibility on 2035 CO2 targets and tariffs/commercial bargains on Chinese imports. The aim is to shield OEMs and suppliers from international competition as the industrial core shifts from conventional engines to clean tech, while largely sticking to the 2035 CO2 targets.
However, for companies willing to invest in the green transition, major hurdles remain around predictability, timing and coherence of the future policy framework:
- Predictability of the future regulatory landscape is essential to make sound investment decisions, yet most of the pieces of the legislative puzzle are still on the table, with major aspects still under negotiation: eligible countries for "made in/with Europe", the mandatory nature of corporate fleet greening, etc. Add to this the unstable nature of the EPP-S&D-RENEW coalition, with some EPP components calling for the IAA to be dropped entirely, and you get a dangerous cocktail of uncertainty.
- Second is the timing: all policy measures will only take effect in real life 2-3 years after their adoption, an eternity in today's business context.
- Last but not least, coherence will be critical: if all these pieces of legislation don’t fit together, they will not only fail to achieve their industrial objectives but also create yet another compliance burden on EU industry, while competitors exploit the loopholes.
2. Deploying 5G and Disruptive Tech Frameworks
The Gazette: As Europe aims to accelerate its digital transition, how can disruptive tech companies successfully navigate the complex EU telecom frameworks and 5G security requirements without stalling innovation?
Thomas Linget: Despite a decade of efforts to build a Digital Single Market, it remains far from reality. Divergent national rules and fragmented capital markets still limit the scaling of disruptive EU companies and their access to venture capital (the “Death Valleys”).
The current framework does not allow many shortcuts. However, ongoing legislative proceedings, such as EU Inc (the “28th regime” for companies) and the Digital Networks Act (DNA), offer an opportunity to identify and advocate for the removal of specific regulatory hurdles that might impede companies' expansion strategies. Given their scale, such files require a large coalition to weigh in on the discussions, unless the ask is very narrow and technical.
Even more strategic for innovative companies is the digital sovereignty agenda: the Cloud and AI Development Act (CADA), the Cybersecurity Act 2 (CSA2) and the Public Procurement Act. These are likely to become the template for future EU legislation on critical technologies.
While the texts are still heavily debated, the direction is unlikely to reverse in today’s geopolitical context, even if the final versions are softened. The EU cloud certification scheme is a case in point: sovereignty criteria were dropped from it and are now back as binding law in CADA.
Companies need to carefully consider future criteria, e.g., European preferences in public tenders (origin requirements, award points, and possible exclusion of bidders from countries without trade agreements), sovereignty assurance levels, or possible exclusions or restrictions on hardware/software from third countries.
Those able to anticipate and adjust their strategy and suppliers' choice to future rules might gain a competitive advantage, especially if they target public contracts or customers in NIS2 "highly critical" or "critical" sectors, which are first in line for their application.
3. Proactive Advocacy in a Shifting Policy Environment
The Gazette: With industrial policy and environmental mandates now blending deeply in Brussels, how must public affairs strategies evolve for companies in the mobility sector to remain proactive rather than reactive?
Thomas Linget: Environmental and industrial policies have always been intertwined in major EU mobility files, but the degree of overlap today is unprecedented, making the ability to bridge both a must.
For instance, decarbonising road transport is no longer a matter for DG CLIMA, GROW and MOVE alone: electrification, raw materials and “Made in Europe” requirements mean DG ENER, DG ENV and DG TRADE must also be mapped and factored in.
Being proactive means treating these files as interconnected and breaking down silos within public affairs teams, so that messaging stays aligned across the board. It also requires a thorough internal analysis of business exposures and dependencies to define clear policy goals and a narrative that resonates with the current geopolitical context.
This blend also makes cross-sector regulation harder for policymakers. Stakeholders who can support them with the right data points and real-world evidence across a broader range of issues can therefore gain a critical edge.
The volatility of majorities in Parliament and, to a lesser extent, in Council also calls for a broader outreach strategy to secure enough support for your policy goals, whatever the coalition scenario. Combined with the cross-sector nature of many of these initiatives, the ability to build broader coalitions, whether vertically along the value chain or horizontally across sectors, is more critical than ever to ensure future advocacy successes.
The Brief
Brussels, decoded, every morning. What happened, what it means, one good dry joke.