Strategic Sectors & Industrial Policy
Special Reports | Autumn 2026 Edition
The Circularity Reality Check: Scaling Europe’s Packaging Rules Without Weakening Industry
An executive dialogue on implementing the Packaging and Packaging Waste Regulation, building a Single Market for recycled polymers, and protecting the competitiveness of Europe’s 48,000 plastics converters.
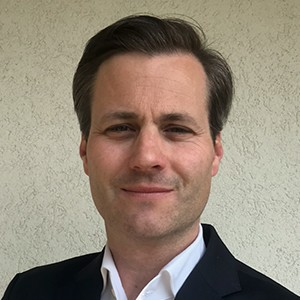
A conversation with Erich Cuaz, Director General of European Plastics Converters (EuPC)
BY AIDA IORDACHE • NOVEMBER 19, 2026
As the European Union’s Packaging and Packaging Waste Regulation moves from legislative text into active application, Europe’s plastics converting sector finds itself on the front line of the bloc’s green transition. Representing nearly 48,000 companies - predominantly SMEs - and 1.3 million workers across the continent, the industry is tasked with delivering ambitious recycled-content and design-for-recycling targets while navigating persistently high energy costs and intense global competition.
For Erich Cuaz, Director General of European Plastics Converters (EuPC), the central challenge facing Brussels is not the environmental ambition of the Packaging and Packaging Waste Regulation, but the risk of regulating demand without building the industrial infrastructure to match it. Citing European Investment Bank and Commission estimates of an €82 billion annual investment gap until 2040 to deliver Europe’s circular economy policies, Cuaz warns that fragmented national verification rules, delayed secondary legislation, and uneven global standards risk penalising European manufacturers while opening the door to cheaper, non-compliant imports.
In an exclusive executive dialogue with The Gazette, Cuaz outlines the structural priorities EU policymakers must address to create a functioning Single Market for secondary raw materials - and explains why bringing hard, frontline manufacturing data into the legislative process early is essential to keeping European industry competitive.
1. Navigating PPWR Packaging Mandates
The Gazette: With the Packaging and Packaging Waste Regulation in active application since August 2026, plastics converters face stringent design-for-recycling and recycled-content targets. What primary structural support and infrastructure updates must EU policymakers prioritize to ensure a stable supply of high-quality circular polymers for converters?
Erich Cuaz: The PPWR can only deliver its environmental objectives if Europe simultaneously builds the industrial infrastructure needed to supply the required recycled materials at competitive cost and consistent quality. For converters, the biggest risk is not the ambition of the regulation itself, but a potential mismatch between ambition, pragmatic implementation, Single Market fragmentation, recycled content availability at a competitive price.
EU policymakers should therefore prioritise investment in collection and sorting infrastructure, while creating a genuine Single Market for secondary raw materials. Quality starts with feedstock. A stable supply of high-quality recyclate therefore depends on fixing several layers at once. Accordingly, the main priorities of EU policy makers and national governments should be:
- harmonised separate collection
- deposit return systems, which yield the cleanest streams
- investment in finer polymer- and colour-specific sorting
- EPR fees modulated to reward recyclable design and to fund sorting capacity
Converters also need recyclate with certified specifications, especially for food contact. That means harmonised quality standards, robust third-party certification, and enhanced traceability. Harmonised rules and clear methodologies for calculating and verifying recycled content and the design-for-recycling criteria are essential. The Commission is already working on these elements, but their rapid and consistent implementation will be critical. Delays or unclear rules leave converters guessing, and that slows down exactly the investments the policy ambition requires..
Traceability across the value chain is also of uppermost importance. Converters need access to reliable data on the origin, quality and recycled content of polymers without having to manage different verification systems for different Member States or suppliers. Today, many companies must hire consultants or invest in software just to manage verification and documentation, a fixed cost that hits SMEs hardest.
According to the European Investment Bank and the European Commission, Europe needs an additional €82 billion of investment a year until 2040 just to implement the circular economy policies it has already adopted. Much of that must come from industry, and industry can only invest and innovate if it stays competitive.
In short, Europe should not only regulate demand for circular polymers; it must also build the necessary infrastructure, mobilize public and private investments into a functioning single market and effective collection, sorting and recycling stages. Otherwise, we risk creating ambitious targets on paper while weakening the industrial base that has to deliver them.
“According to the European Investment Bank and the European Commission, Europe needs an additional €82 billion of investment a year until 2040 just to implement the circular economy policies it has already adopted.”
2. Supply Chain Friction and Costs
The Gazette: Transitioning production lines to meet the new EU sustainability mandates involves heavy administrative tracking and capital reallocation. How can European converting enterprises successfully integrate these complex regulatory requirements into their active business plans without undermining their operational margins?
Erich Cuaz: For converting companies, the most effective approach is to integrate PPWR directly into strategic business planning. The requirements affect product design, raw-material sourcing, production technology, quality management, customer specifications and data management, so they need to be considered together rather than department by department.
The first priority should be to translate the PPWR into a clear roadmap for each product family: what will need to change, when, what investment will be required and where the additional cost will arise. This allows companies to distinguish between changes that are immediately necessary and those linked to requirements that will only become applicable later. That is particularly important because several detailed delegated acts (secondary legislation) are still being developed by the European Commission.
Secondly, companies need to secure reliable data on material composition, recycled content, suppliers, recyclability and product specifications should become part of the normal product-development and procurement workflow. This can turn compliance data into a business asset rather than simply an administrative cost.
Still, there is a limit to what companies can absorb through efficiency gains. Converters are already operating under significant energy, labour and raw-material cost pressures. Europe therefore needs a regulatory environment that rewards investments in circularity rather than simply transferring the cost of the transition downstream. Financial support for conversion of equipment, recycling infrastructure and digitalisation can help, but equally important are predictable rules, harmonisation and sufficient lead times for investment decisions.
Ultimately, European competitiveness has to remain part of the PPWR implementation equation. If the cost of complying with Europe's circularity requirements becomes structurally higher for European converters than for producers outside Europe, there is a risk that domestic production and investment are affected while European products are increasingly replaced by imports. That would not necessarily reduce the environmental impact of packaging. Europe therefore needs to ensure that the transition to circular packaging strengthens European manufacturing rather than unintentionally driving industrial and carbon leakage.
3. Strategic Advocacy Amid Global Competition
The Gazette: As European converters navigate intense global market pressures and high energy costs, what critical levers should industrial public affairs strategies utilize to ensure that the practical data of manufacturing operators is heard before new legislative drafts are finalized?
Erich Cuaz: Effective policymaking at the EU level must better reflect the economic and business realities under which our industry operates. The legislator has a lot to gain in being informed of the practical experience of those who operate across the value chain. European plastics converters, almost 48,000 companies, mostly SMEs, employing 1.3 million people, are facing high energy costs, increasing regulatory demands and intense international competition. In this context, it is essential that policymakers understand the practical impact, and sometimes unintended implications, of new legislation before proposals are finalised.
EuPC’s role is to bring credible, evidence-based input from industry to the European institutions at an early stage. By collecting data from manufacturers on production costs, energy consumption, trade statistics, investment needs, we can help identify and anticipate unintended consequences and ensure that proposed measures are both achievable and proportionate. Because converters speak with one voice through EuPC, that evidence carries real weight. And our work does not stop once a law is adopted: much of what decides whether legislation works in practice is set later, via secondary legislation, in the technical rules and standards.
The industry’s practical experience must inform policymaking from the outset, not become an afterthought once decisions have been made.
“European plastics converters, almost 48,000 companies, mostly SMEs, employing 1.3 million people, are facing high energy costs, increasing regulatory demands and intense international competition.”
The Brief
Brussels, decoded, every morning. What happened, what it means, one good dry joke.